The Customer Looks Legitimate. Is the Transaction?
Picture this.
A buyer wants to purchase a high-value property. They provide their identification documents, pass your Know Your Customer (KYC) checks, and appear professional throughout the process. Their paperwork looks complete, and nothing immediately raises concern.
You move forward, confident that you've done your due diligence.
Then something changes. The buyer asks for the purchase to be funded through a company you've never heard of. The money comes from an unrelated third party. When you ask about the arrangement, the explanation doesn't quite add up.
Suddenly, a customer who passed KYC doesn't look quite so straightforward.
Here's the problem: verifying someone's identity is not the same as understanding their financial activities, the source of their money, or the risks associated with a transaction.
For real estate sales agents, buyers' agents, property developers, conveyancers and accountants, this distinction matters. Property transactions can involve large sums, complex ownership structures and multiple parties. These features can create opportunities for criminals to disguise the origins of illicit funds.
KYC is an essential first step. But it isn't the finish line.
Let's look at why a customer can pass KYC and still present a money laundering risk, and what you can do to identify warning signs before they become serious compliance problems.
1. KYC Verifies Identity, Not the Whole Story
KYC is designed to establish who a customer is. Depending on the applicable requirements and risk profile, checks may include verifying identity, understanding the customer's circumstances and identifying relevant risk factors.
But a genuine identity document doesn't prove that a customer's money comes from a legitimate source.
Think of KYC as checking the person at the front door. Customer due diligence (CDD) goes further by examining the purpose of the relationship, the risks involved and, where appropriate, the origin of the funds.
Consider two buyers purchasing properties worth $1.5 million each.
- Buyer A provides identification, explains that the purchase is funded by savings and proceeds from selling another property, and supplies supporting documents consistent with that explanation.
- Buyer B provides equally valid identification but plans to use funds from several unrelated companies, cannot clearly explain the ownership structure and gives conflicting answers about the money's origin.
Both buyers may pass identity verification. Their risk profiles, however, could be very different.
According to AUSTRAC, understanding a customer's source of funds and source of wealth can help businesses identify and manage money laundering risks.
The lesson: Passing KYC of an individual doesn't automatically make a customer low risk. You need to understand the bigger picture and entities involved.
2. Why Real Estate Can Attract Money Laundering
Property is attractive to criminals for several reasons. Transactions can involve substantial amounts of money, ownership can be structured through companies or trusts, and property can serve as both an asset and a way to disguise the origins of wealth.
For professionals working across real estate, conveyancing and accounting, the risk may not be obvious at first.
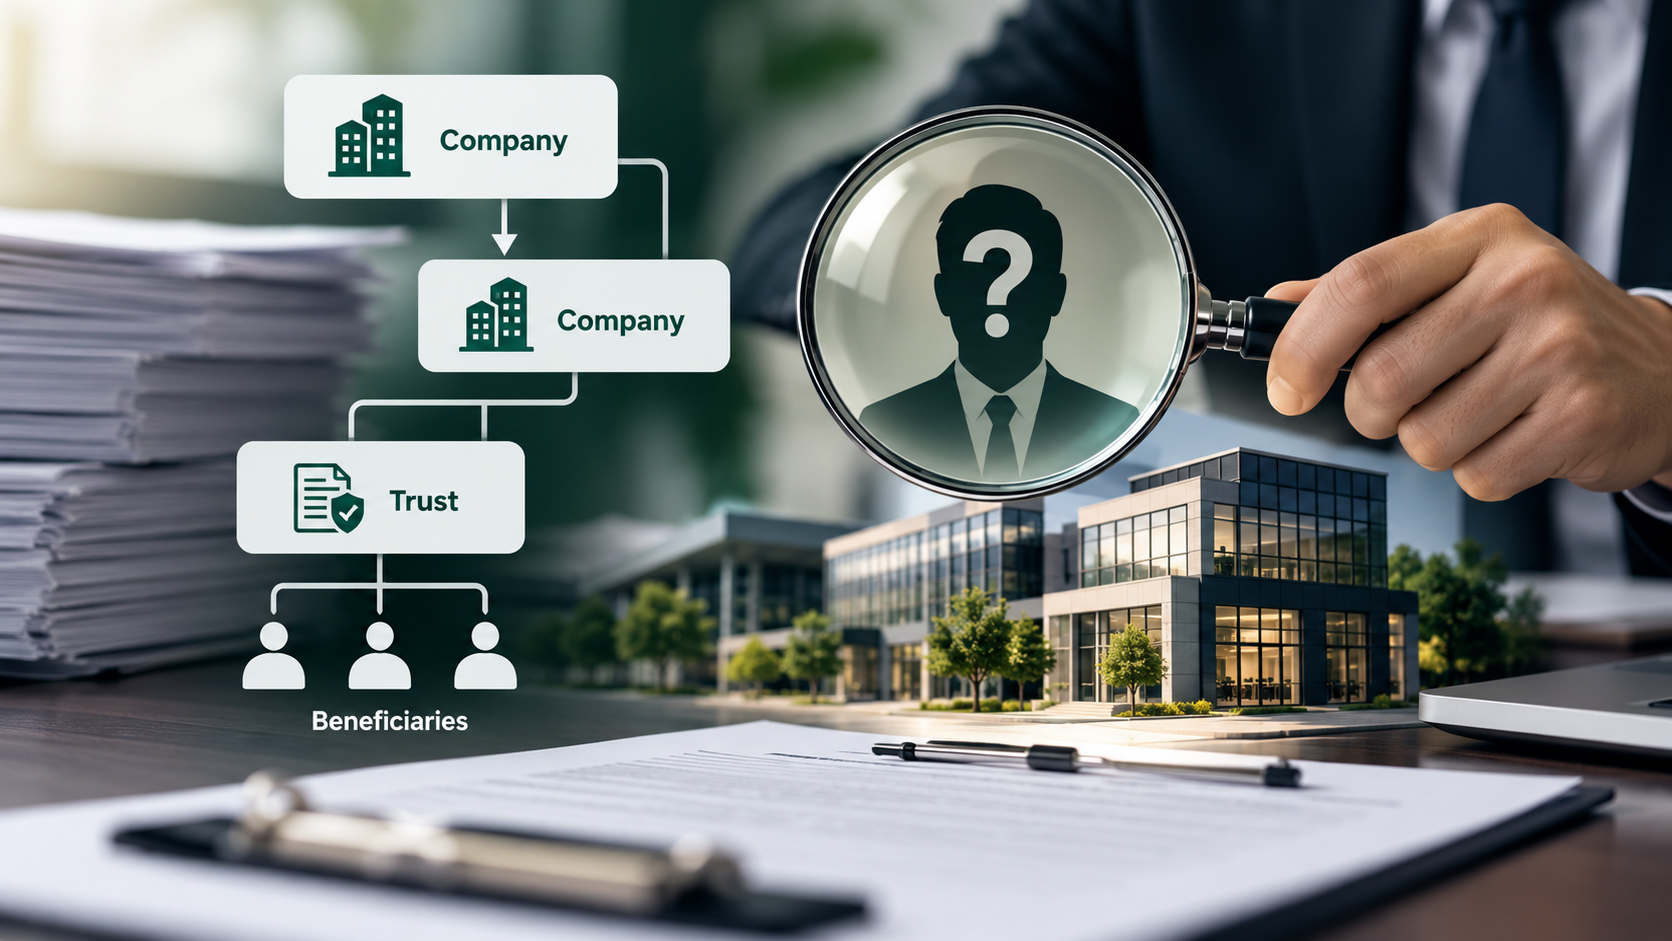
Complex ownership structures can hide the real buyer
Imagine a buyer who wants to purchase a commercial property through a company. That company is owned by another company, which is linked to a trust with several beneficiaries.
Such arrangements can be legitimate. Businesses use companies and trusts for many ordinary commercial and estate-planning reasons.
The concern arises when you cannot reasonably establish who ultimately owns or controls the structure, why it is being used or how it relates to the transaction.
Understanding the beneficial owner, where required, helps reveal who is really behind a customer rather than stopping at the name on the paperwork.
The money doesn't match the customer's profile
A buyer claims to operate a small business but wants to purchase several expensive properties in quick succession. Their stated income and business activities don't appear consistent with the scale of the purchases.
There may be a perfectly legitimate explanation, such as an inheritance, a recent business sale or investment income.
However, the mismatch deserves attention.
The question isn't whether someone is wealthy enough to buy a property. It's whether the available information provides a reasonable explanation for the funds and the transaction.
Third-party payments complicate the picture
A buyer passes KYC, but the deposit arrives from a company or individual who isn't named in the purchase documents.
Perhaps a family member is helping with the purchase. Perhaps a related company is providing a legitimate loan.
Or perhaps the third party is being used to obscure the actual source of the money.
The payment arrangement should be understood and assessed in context, rather than accepted simply because the funds have arrived.
AUSTRAC identifies unexplained wealth, unusual third-party transfers and complex funding arrangements among the indicators that may warrant further examination in real estate transactions.
3. Five Red Flags That Deserve a Closer Look
One unusual detail doesn't automatically mean money laundering is taking place. What matters is the overall picture, including whether the customer's explanation is credible and supported by available evidence.
Watch for these warning signs.
1. Unexplained sources of funds
The customer cannot clearly explain how they obtained the money for the purchase, or their explanation changes during the transaction.
Ask what generated the funds and what evidence would reasonably support the explanation.
2. Unusual urgency
The customer pressures you to complete the transaction quickly, discourages reasonable questions or seems unusually reluctant to provide information.
Urgency alone is not proof of wrongdoing. But pressure to bypass established checks should never replace a proper risk assessment.
3. Unnecessarily complicated payment arrangements
Payments come from multiple unrelated parties, offshore accounts or private lenders without a clear commercial explanation.
Understand the parties involved, their relationship to the customer and the purpose of the arrangement.
4. Unclear beneficial ownership
The customer uses companies, trusts or nominees, but the information provided doesn't adequately explain who owns or controls them.
Review the structure and obtain further information where required by the customer's risk profile and applicable obligations.
5. Transaction activity that doesn't make sense
A customer repeatedly buys and sells properties, makes unusual changes to the purchasing entity or proposes transactions that appear to have no clear commercial or lawful purpose.
Ask whether the activity is consistent with what you know about the customer and the intended transaction.
These indicators should trigger proportionate investigation, not automatic accusations. Legitimate customers can have complex finances, and unusual behaviour can have innocent explanations.
4. What Should You Do After a Customer Passes KYC?
The answer isn't to repeat every check for every customer. It's to build a risk-based process that responds when new information changes your understanding of the customer.
Step 1: Understand the purpose of the transaction
Establish why the customer is using your services, what they intend to do and whether the transaction makes sense in context.
For example, is a company buying property for its own business operations, as an investment or on behalf of someone else?
Step 2: Assess source of funds and source of wealth
These terms sound similar, but they answer different questions.
- Source of funds: Where did the money for this particular transaction come from, and how was it obtained?
- Source of wealth: How did the customer accumulate their overall wealth?
Depending on the circumstances, relevant evidence may include bank statements, sale agreements, loan documents, tax records or inheritance documents.
A bank transfer alone doesn't establish the underlying source of the money. You need to consider how the customer obtained it and whether the explanation is consistent with the evidence.
Step 3: Check who is behind the transaction
Identify and assess beneficial owners, relevant third parties and other persons where required. Consider whether ownership arrangements, control or funding relationships create risks that need further investigation.
Step 4: Reassess risk when circumstances change
KYC isn't a one-time exercise. New information, changes in ownership, unusual behaviour or unexpected funding arrangements may mean the customer's risk profile needs to be reviewed.
Ongoing customer due diligence helps businesses respond to those changes rather than relying indefinitely on information collected at onboarding.
Step 5: Document your decisions and escalate concerns
Record what raised the concern, what you checked, what evidence you obtained and why you reached your decision.
If concerns remain unresolved, follow your organisation's AML/CTF procedures and seek advice from the appropriate compliance personnel. Where applicable reporting obligations are triggered, follow the relevant requirements.
Don't ignore a concern simply because the customer is an important client or the transaction is commercially valuable.
5. The Real Cost of Stopping at KYC
Imagine discovering a serious concern just before settlement.
Your team now has to review documents, reconstruct the payment trail, consult compliance advisers and explain why an earlier decision was made. The transaction may be delayed, internal resources may be diverted and your organisation's reputation could be affected.
More importantly, inadequate customer due diligence can leave your business exposed to regulatory consequences when applicable obligations have not been met.
For property developers, agents, conveyancers and accountants, effective AML controls aren't just administrative tasks. They're part of protecting the business, its people and the integrity of the transactions it facilitates.
A well-designed process helps teams identify concerns earlier, make better-informed decisions and create a clear record of their reasoning.
6. How AML SoftServe Can Help
Your team shouldn't have to rely on instinct, scattered spreadsheets or inconsistent manual checks to manage customer risk.
At AML SoftServe, the focus is on helping businesses strengthen their approach to anti-money laundering compliance through practical processes and technology-enabled support.
Depending on your business needs, that may include improving customer due diligence workflows, supporting risk assessment, organising compliance information and strengthening the way your team identifies and responds to potential red flags.
The goal is straightforward: help your team move beyond simply asking, "Have we verified this customer's identity?" and towards asking, "Do we understand the customer, the transaction and the risks involved?"
Visit amlsoftserve.com.au to explore how AML SoftServe can support your compliance needs.
KYC Is the Beginning, Not the Finish Line
A customer can provide genuine identification, answer every onboarding question and still present a money laundering risk. The warning signs may emerge later, when the source of funds becomes unclear, ownership structures grow complicated or transaction behaviour changes.
That's why effective AML compliance goes beyond collecting documents.
It means understanding the customer, examining the transaction in context, checking information when necessary and responding appropriately when something doesn't add up.
For real estate professionals, conveyancers, property developers and accountants, the question isn't simply whether your customer passed KYC.
It's whether you have enough reliable information to understand the risk they're bringing into your business.
If your current process stops at identity verification, it may be time to look at what happens next.
Ready to strengthen your AML compliance approach? Visit AML SoftServe to discuss how your business can build more effective customer due diligence processes and manage risk with greater confidence.
This article provides general educational information, not legal advice. AML/CTF obligations depend on your business, the services you provide and the applicable legislation.